The first rule of retirement planning is also the easiest to follow. If you have a regular job, then your EPF account becomes a forced saving plan.
Given the power of compounding, even a small contribution will help a lot.
The 10% rule is crucial for self-employed professionals and others who are not covered by the EPF umbrella. They can opt for mutual funds, choosing the ones that suit their risk appetite and age profile. However, you need to have the discipline to put away the given sum on a regular basis.
And don’t underestimate the significance of the savings in the first few years. Assuming that a 25-year-old investor puts away a fixed amount every month, his savings in the first five years will account for 44% of his total corpus when he is 60 years old. The later you start, the more you will need to save. If you have started late, say in your 40s or 50s, you will have to invest up to 20-25 % of your income if you want a comfortable retirement.
Start an SIP in a mutual fund and automate the process by giving an ECS mandate to your bank. In this way, your retirement planning will stay on track.
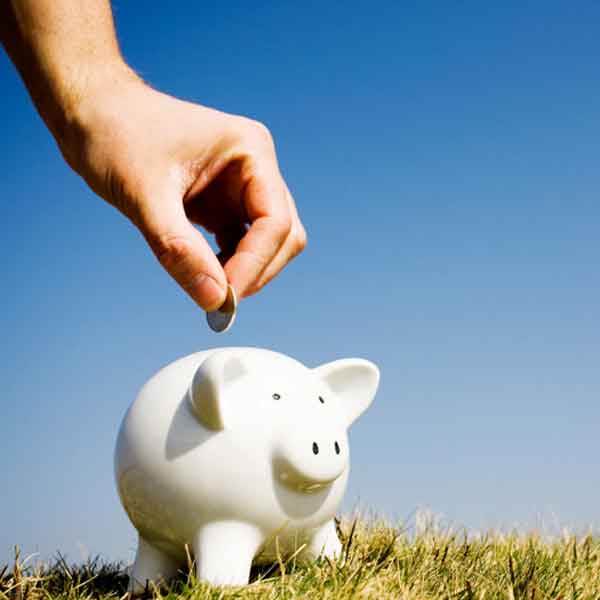
One of the biggest mistakes investors make is keeping their retirement contribution unchanged even after receiving salary hikes or business income growth. While income increases over time, lifestyle expenses often rise at the same pace, leaving little additional money for long-term wealth creation.
Make it a habit to increase your retirement investments whenever your earnings grow. Even a small annual increase in your monthly SIP or retirement contribution can significantly boost your retirement corpus because of the power of compounding over several decades.
For example, if you start by investing 10% of your income and gradually increase that amount every time your salary increases, your retirement fund can grow several times larger than if you kept your investment fixed. This simple habit helps ensure that inflation and future financial needs do not erode your retirement goals.
Remember, your future lifestyle depends not only on how much you earn today but also on how consistently you increase your investments throughout your career.
Every time you receive a salary hike, promotion, bonus, or business profit, increase your SIP or retirement investment by at least 5–10%. Automating this increase can help you build a much larger retirement corpus without affecting your lifestyle significantly.
This might sound weird, but every time you change jobs, your retirement planning is at a grave risk. This is because you have the option to withdraw your PF balance at that time or transfer it to the account with the new employer. Besides, there is the option to withdraw your PF amount if you need the money for specific purposes, including your child’s marriage, buying or building a house, or in medical emergencies. Dipping into the corpus before you retire prevents your money to gain from the power of compounding. Don’t underestimate what this can do to your retirement savings over the long term. A person with a basic salary of 25,000 a month at the age of 25 can accumulate 1.65 crore in the PF over a period of 35 years. This is based on the assumption that his income will rise by 10% every year.
Yet, many people are unable to reach the 1 crore milestone in their PF accounts. Although the paperwork is minimal, a lot of people prefer to withdraw their PF money when they change jobs or for other purposes. This, despite the fact that the government discourages you from withdrawing the money. The withdrawals from the EPF within five years of joining are taxable.
The sudden flush of liquidity can trigger a spending spree and ill-planned decisions that can cripple your financial planning. Often, the money goes into discretionary spending, which means your retirement planning is back at square one. A late start means a smaller corpus even if you start investing more.
Whenever you change jobs, transfer your EPF balance instead of withdrawing it. Preserve your retirement corpus and allow compounding to work uninterrupted for your future financial security.
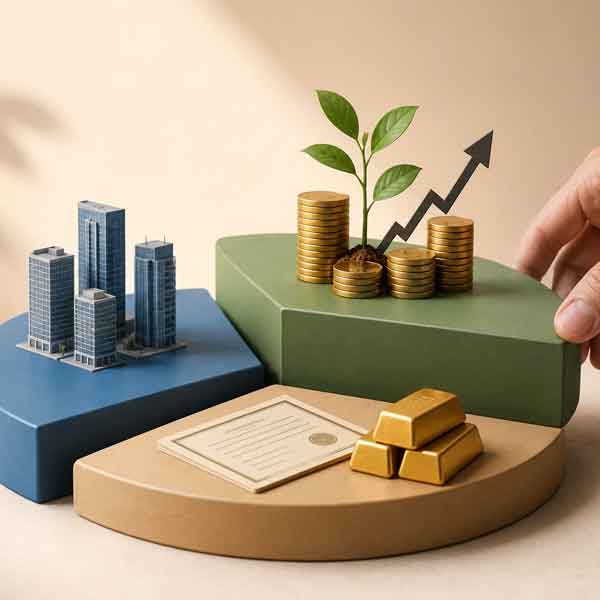
An investment portfolio’s performance is determined more by its asset allocation than by the returns from individual investments or market timing. How much you have when you attend your last day at work will depend on how you divided your retirement savings between stocks, fixed income and other asset classes.
Even within equities, the type of stocks (or equity funds) in your portfolio should vary with age.
This is not a hard and fast rule and should also take into account the financial situation of the individual. It assumes that all people at a certain age will have the same risk appetite. This is not true. A 45-year-old person with a good income and few dependants will be able to take on more risk than someone who is 30 but has a low and unsteady income.
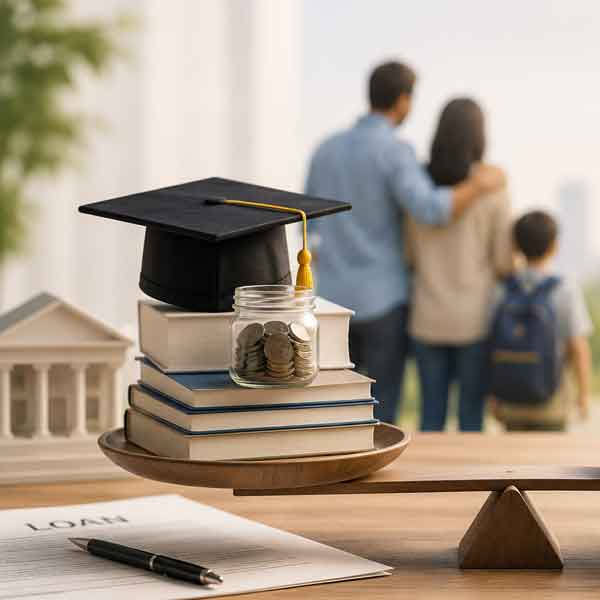
Providing your children with the best education is a wonderful goal, but it should not come at the cost of your own financial security. Many parents prioritize education and other family expenses so heavily that they neglect or even withdraw from their retirement savings. This can create financial challenges later in life when regular income stops.
Unlike education expenses, which can often be financed through education loans, retirement cannot be funded through borrowing. Banks and financial institutions readily offer loans for higher education, homes, vehicles, and other major expenses, but there is no loan available to support your retirement years.
Building your retirement corpus should therefore remain a top financial priority. Continue investing consistently while planning separately for your child's education. Education loans can help bridge funding gaps and also provide tax benefits on the interest paid under applicable tax laws.
A balanced financial plan ensures that your children receive quality education without compromising your future financial independence. By protecting your retirement savings today, you reduce the likelihood of becoming financially dependent on your children later in life.
Consider an education loan instead of withdrawing from your retirement corpus. It not only preserves your long-term investments but also encourages financial responsibility and repayment discipline in your child while safeguarding your own retirement goals.
Migration of children and collapse of joint family system
Increased life expectancy
Increased expenses on health
Pensions, if any, Insufficient to sustain the living standards
Increased Cost of Living/Spending patterns
Retirement saving should last for at least 25 years
Download our Android or iOS App for Tracking your Portfolio
Note : Mutual Funds investments are subject to market risks, read all scheme related documents carefully.